How to Check US Sales Tax and Chargeback Risk: Separate Liability from Order Evidence
15 parts · 2 checkpoints
Show all 15 parts
- 01US Tax Dispute Desk
- 02Plain terms
- 03Two-line risk table
- 04Risk nodes
- 05Reason-code evidence
- 06Payment and support relay
- 07Chargeback Evidence Builder
- 08Sales Tax Trigger Boundary
- 09Order review actions
- 10Monthly pause/continue
- 11Turn the risk table into the next action
- 12Quick Check, has a checkpoint
- 13US Tax and Dispute pressure-check practice
- 14US tax and dispute risk: what to record
- 15Compliance paths after tax and dispute review
Shopify collecting tax at checkout does not finish US tax responsibility, and a shipped order does not automatically have enough dispute evidence. Separate the order timeline into the same five jobs the body names: tax, capture, shipping, refund promise and dispute evidence, before choosing whether to continue, verify, refund to stop loss, or pause scaling.
This lesson answers
US Tax Dispute Desk
Use one disputed order to separate tax, capture, shipping, refund, and evidence.
Take one US order: the buyer saw sales tax, AVS/CVV had warnings, the warehouse shipped, the buyer says it never arrived, and a chargeback starts. Do not collapse this into “US risk.” Tax, capture, shipping, refund promise, and dispute evidence are five different jobs with different owners and evidence.
Follow this one order first: tax checks state liability and setup, capture checks manual capture and risk signals, shipping checks fulfillment records, refund promise checks page and support wording, and chargeback response checks reason-code evidence. The table only works after these five jobs are separated.
Judgment: One order can carry both a state review and a dispute action. Decision condition: Each line needs its own facts and pause scope. Evidence: Keep the state signal, order timeline, and customer touchpoints distinct. Scope: State scaling and one order’s fulfillment are not the same switch. Take away: Write which line is limiting which move first. Do not treat collected tax or a shipped parcel as permission to continue all five jobs.
- US tax and dispute risk table: Artifact
- sales tax / chargeback: Two lines
- Not tax advice: Boundary
Lesson deliverable
- Tax liability and state setup
- High-risk order review actions
- Reason-code evidence packs
- Page, support, and fulfillment promises align
- Monthly fraud/dispute ratio review
Plain terms
Separate tax terms from dispute terms first.
This material does not make you a tax or payment expert, but it shows which system, order, owner, and evidence each term touches.
- Sales tax
US sales tax is a state-level responsibility and setup problem. Shopify can help calculate and collect, but registration, filing, remittance, and automated filing depend on business facts and state liability. Example: Turning on tax collection is not the whole obligation. You still need state, reason, reviewer, and accounting export responsibility.
- Tax liability
Tax liability is whether you may need to collect, file, and remit in a state. Shopify tax liability insights can help monitor, but they do not replace tax authority or professional advice. Example: When a state approaches a threshold, record state, sales, registration status, and reviewer before changing promises.
- Chargeback
A chargeback is a cardholder dispute through the issuing bank. It is not a normal refund ticket; evidence follows the reason code and the issuer usually decides. Example: Tracking alone is not always enough. Fraud, not received, product unacceptable, and credit not processed require different evidence.
- Fraud analysis
Fraud analysis is Shopify order-risk signaling, including AVS, CVV, IP, address mismatch, and unusual purchase patterns. Its value is before fulfillment. Example: If a high-risk order is fulfilled, later evidence is weak; better actions are verify, pause, cancel, or refund first.
- AVS / CVV
AVS checks billing address match; CVV checks card security code. They are not final proof, but they help decide manual review. Example: When billing, shipping, IP country, and CVV signals all look unusual, do not auto-fulfill.
- Manual capture
Manual capture lets the team review risk before capturing funds and fulfilling. It is not for slowing every order; it creates a review window for risky ones. Example: Verify high-risk orders before capture, cancel, or refund; do not ship first and hope.
- Feed
A feed is the product data file sent to ad or commerce platforms. It matters here because wrong price, shipping promise, return information, or product status can affect ad promises and later dispute evidence. Example: If the feed still says a product is available while the page and warehouse are out of stock, later not received or product unacceptable disputes become harder to explain.
- Consent
Consent is the user permission state for data processing, email marketing, or remarketing. In dispute work, order evidence and marketing actions should not bypass user choice. Example: After a user rejects marketing tracking, the team should not keep remarketing scripts firing under the old consent state just to gather evidence.
- Checkout
Checkout is where the buyer sees final price, tax, shipping, refund promise, and subscription choices before payment. Many US tax and dispute issues become visible only there. Example: If the page promises free returns but checkout or policy pages do not explain conditions, later credit not processed or product unacceptable disputes are harder to handle.
- Fraud/dispute ratio
Fraud/dispute ratio is a risk signal watched by payment networks and acquirers, and you should be able to compute it on the spot: (fraud plus dispute count this month) / settled transactions this month. Classroom example: 6 disputes against 480 settled transactions is 6 / 480 = 1.25%; at a $15 dispute fee that is $90 for the month. Whether 1.25% triggers a processor warning depends on that network threshold and its monthly count floor (Visa VAMP carries a fraud-plus-dispute count gate of its own), so do not read one ratio as either safe or flagged; write the ratio, the SKUs and the channels into the monthly record and compare once you have a sourced threshold. Keep reading the trend, source and region; one month is not an annualised conclusion. Example: If not received rises for one SKU or channel, inspect delivery promise, tracking, and support communication first.
Two-line risk table
Tax responsibility and dispute governance do not replace each other.
The US tax and dispute risk table starts with two lines: sales tax for state responsibility and setup; dispute for order risk, evidence, and monthly fraud/dispute rates.
Job, evidence and the common misread
Tax responsibility line
- Job
- Decide which states may require collection, registration, filing, remittance, and how Shopify setup maps to that.
- Evidence
- State liability record, Shopify tax setup, tax ID, automated filing status, accounting exports.
- Common mistake
- Mistaking Shopify can calculate for tax responsibility is solved.
Dispute line
- Job
- Review high-risk orders before fulfillment, prepare reason-code evidence, and monitor ratios and sources monthly.
- Evidence
- Fraud analysis, AVS/CVV, IP, tracking, support messages, refund records, reason code.
- Common mistake
- Waiting for the bank notice before finding tracking and messages.
Judgment: The tax line answers state responsibility; the dispute line answers an order action. Decision condition: Classify the current signal before choosing a move. Evidence: The tax line keeps state facts and setup; the dispute line keeps payment, fulfillment, and communication timelines. Scope: A state review can limit scaling, while one order risk can limit capture or fulfillment. Take away: Give each line its own responsible lead, next move, and recovery condition. Do not use “US risk is normal” to cover two different conclusions.
Risk nodes
Every node needs evidence and a responsible lead.
Do not leave the US risk field pending. Click a node, read its pause signal and responsible lead, then carry the decision into your own store review.
Choose a case: Tax liability
- Check
- Which states may create liability, registration, filing, remittance, and whether tax service or professional advice is needed.
- Evidence
- Shopify US taxes, tax liability insights, state records, registration status, accounting export responsible lead.
- Pause signal
- Collecting at checkout without knowing why that state is being collected.
- Responsible lead
- Finance / tax coordination responsible lead
- Check
- Whether tax ID, shipping tax, override, automated filing, accounting exports, and state setup are recorded.
- Evidence
- Admin path record, setting change log, accounting reports, review date.
- Pause signal
- Settings changed, but no one knows affected orders and reports.
- Responsible lead
- Finance / Shopify admin responsible lead
- Check
- Whether AVS/CVV, IP, address mismatch, velocity, odd email, and repeated-card patterns enter pre-fulfillment review.
- Evidence
- Fraud analysis, order details, payment logs, manual review notes.
- Pause signal
- High-risk orders still auto-capture and auto-fulfill.
- Responsible lead
- Order review / fulfillment responsible lead
- Check
- Whether fraudulent, product not received, product unacceptable, and credit not processed each have their own evidence pack.
- Evidence
- Reason code, tracking, delivery, page version, policy page, support messages, refund record.
- Pause signal
- Every dispute uses the same generic explanation, regardless of reason.
- Responsible lead
- Support / payment responsible lead
- Check
- Whether shipping, refund, returns, FAQ, order emails, and support scripts match actual fulfillment.
- Evidence
- Page versions, policy pages, order emails, support logs, refund receipts.
- Pause signal
- Page promises 3-5 day delivery, while carrier and support records show frequent delays.
- Responsible lead
- Content / support responsible lead
- Check
- Monthly trend, SKU, channel, region, and reason distribution for fraud + dispute / settled transactions.
- Evidence
- Payment dashboard, Shopify, dispute export, channel/ad source, monthly review sheet.
- Pause signal
- Rising disputes only show up in finance reports and never change order review or page promises.
- Responsible lead
- Finance / risk responsible lead
Reason-code evidence
Dispute response cannot rely on one generic template.
Different reason codes need different evidence. The team should know before fulfillment what evidence may be needed.
Row by row: Evidence to prepare, Operating action
| Reason, evidence and action | Evidence to prepare | Operating action |
|---|---|---|
| Fraudulent / Unrecognized | AVS/CVV, IP, billing address, statement descriptor, order confirmation email, customer confirmation. | Verify high-risk orders first; use manual capture, cancel, or refund when needed. |
| Product not received | Tracking, delivery confirmation, fulfillment time, delay communication, delivery-promise version. | Communicate before promise misses become disputes; reship or refund when needed. |
| Product unacceptable | Product page version, specifications, photos, support messages, return record. | When page promise and fulfillment disagree, fix page and support scripts first. |
| Credit not processed | Refund time, ARN, payment record, customer confirmation, support explanation. | Send refund proof proactively to reduce secondary disputes. |
| Duplicate / General | Transaction ID, order ID, payment time, messages, cancellation or compensation record. | Align order, transaction, and support timeline before submitting evidence. |
Payment and support relay
Dispute evidence does not start after the bank notice. It comes from payment, support, fulfillment, and page promises.
Carry the decision back to the upstream work. Payment gives transaction and refund evidence, support gives customer wording and handling records, fulfillment gives shipment facts, finance shows whether the loss damages cash rhythm, and CRO shows which page promise needs repair.
- Payment gateway: Payment status, capture mode, refund records, transaction ID, ARN, payout deduction, and dispute state.
- Support and post-purchase: Write into support-log and page-promise columns to tell misunderstanding, fulfillment delay, or page-promise failure apart.
- Shipping and fulfillment: Shipping profile, carrier scans, tracking, fulfillment time, delay record, return address, and exception handling record.
- Real order cost: Write into monthly-review column to judge one-off loss versus SKU, channel, and cash-rhythm damage.
- Page roles: Write into customer-touchpoint column to decide PDP, policy page, checkout, support template, or ad-promise changes.
Minimum standard
Every US dispute or tax exception must trace from order ID to payment record, support ticket, shipment state, page version, and finance impact. If it cannot, do not scale budget and do not let the warehouse ship high-risk orders first.
Minimum record: order ID, transaction ID, refund or ARN, ticket ID, tracking, page version, reason code, current move, responsible lead, and review date.
Chargeback Evidence Builder
Turn one real scenario into a submit-ready evidence pack.
Teams often know the reason code but still lack the next records, proof, and timeline. Choose the closest dispute scenario and the selected card as the evidence pack.
Choose a case: Not received: delivery promise broke
- Buyer story
- The 20oz tumbler page promises delivery in 3-5 business days, and ads repeat fast delivery. A recent US batch is still in transit on day 8, and buyers file Product not received disputes.
- Weak response
- Uploading tracking alone misses the page promise, order email, delay notice, and whether the team proactively reshipped or refunded.
- Evidence pack fields
- Order timeline: order, capture, fulfillment, first scan, latest scan. Customer promise: PDP delivery copy, shipping policy, order confirmation email. Communication evidence: delay notice, support reply, reship or refund option. Fulfillment pre-risk: supplier, carrier, promised SLA, actual scans, delay threshold, affected SKU/channel. Operating writeback: if one SKU concentrates delays, pause fast-delivery ad promises and the matching ad source.
- Evidence Submission Pack
- Evidence Submission Pack: one-page order timeline, reason-code evidence map, labeled screenshots, file names, submission deadline, evidence gap, and refund-to-stop-loss decision.
- Next move
- Add delay communication and a reship/refund path before submitting evidence; also bring the delivery promise back inside real fulfillment capacity.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: order ID, Product not received reason code, delivery-promise page version, supplier, carrier, promised SLA, latest carrier scan, delay-notice time, support responsible lead, last verification date, and next reship/refund move.
- Buyer story
- A $148 US order is marked high risk: CVV passes, but billing state, shipping state, and IP country do not align, and the email looks disposable. Warehouse wants to ship because inventory is available.
- Weak response
- Delivery does not prove cardholder authorization. Fraud disputes need authorization, AVS/CVV, IP, customer confirmation, and review notes first.
- Evidence pack fields
- Payment signals: AVS, CVV, IP country, billing address, payment status. Manual review: customer contact, call/email record, order note. Capture strategy: manual capture or Flow pauses high-risk orders. Outcome: cancel, refund, or leave uncaptured when unverified instead of shipping first.
- Evidence Submission Pack
- Evidence Submission Pack: authorization timeline, AVS/CVV plus address/IP mismatch, customer confirmation, manual-review note, uncaptured/cancel/refund decision, and reason not to fight.
- Next move
- Pause capture and fulfillment, ask for confirmation, then cancel or refund if the risk remains unexplained.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: order ID, Fraudulent / Unrecognized reason code, AVS/CVV, IP/billing/shipping conflict, customer confirmation, capture state, payment responsible lead, and escalation record.
- Buyer story
- A buyer returns a tumbler. Support says refund will happen but sends no proof. Seven days later the buyer files Credit not processed because they think the merchant is delaying.
- Weak response
- Saying we refunded is weaker than showing refund time, payment record, ARN or traceable proof, and the customer notification time.
- Evidence pack fields
- Refund fact: time, amount, order ID, transaction ID, ARN or payment record. Return fact: return shipment, receiving scan, inspection record. Support fact: promise time, proof-sent time, buyer confirmation. Process fix: automatically send refund proof so buyers do not guess.
- Evidence Submission Pack
- Evidence Submission Pack: refund timeline, ARN/payment record, return scan, support promise and notice screenshots, arrival window, proof-resend time, and accept-loss boundary.
- Next move
- Send refund proof and timeline before submitting evidence; add refund-confirmation email to the support playbook.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: order ID, Credit not processed reason code, refund time, ARN/payment record, return scan, support notice time, support responsible lead, and recovery condition.
Fields to verify before submission
- Order and capture timeline: Order time, authorization time, capture time, transaction ID, amount, currency, and capture state, so the team first knows whether funds were actually captured.
- AVS/CVV and risk signals: AVS/CVV, IP, billing address, shipping address, email, velocity, fraud analysis, and manual-review notes belong in one row, so high-risk orders do not become tracking-only cases.
- Fulfillment and logistics trail: Fulfillment time, carrier, first scan, latest scan, delivery or exception, delay notice, and reship record show whether not received is an evidence gap or a promise failure.
- Support and customer record: Order confirmation, buyer confirmation, support ticket, refund promise, delay explanation, and whether the buyer will withdraw the dispute should be screenshot-ready or exportable.
- Page and policy snapshots: Keep the purchase-time PDP version, shipping policy, refund policy, order email, and checkout tax display so later page edits do not erase what the buyer saw.
- Loss-control or escalation decision: Write the evidence gap, submission deadline, refund-to-stop-loss choice, accept-dispute choice, payment-provider escalation, or external tax review as the next action.
Sales Tax Trigger Boundary
Tax issues need trigger, review, and pause scope, not instinct.
This is not tax advice; it is the operating boundary. When state signals, checkout tax, or new-state scaling appear, the team needs first checks, prohibited moves, and missing fields.
Choose a case: Approaching state liability signal
- Trigger
- Shopify tax liability insights shows a state with potential liability reason and date, but the team has no registration status or responsible reviewer.
- First check
- Record state, sales/order basis, signal date, registration status, and whether professional confirmation is needed.
- Do not
- Do not treat the signal as a tax conclusion, and do not scale that state while responsibility is unclear.
- Minimum worksheet fields
- State and signal reason; Trailing sales / order count; Registration status and tax ID; Accounting export responsible lead
- Continue boundary
- Continue low-risk orders; pause scaling into that state until the responsibility record and reviewer are clear.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: state, potential liability reason/date, trailing sales/orders, registration status, responsible reviewer, last verification date, and whether outside tax review is escalated.
- Trigger
- Buyers see sales tax at checkout, but the team cannot explain state, reason, registration, filing lead, or accounting export.
- First check
- Check Shopify US taxes setup, tax ID, shipping tax, override, automated filing status, and accounting reports.
- Do not
- Do not mistake system tax calculation for assigned filing and remittance responsibility.
- Minimum worksheet fields
- Admin setup record; Tax ID / registration status; Shipping tax and override; Filing / remittance or advisor responsibility
- Continue boundary
- Fill records and accounting exports first; unclear records mean US tax setup is not a market-ready signal.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: checkout tax screenshot, Shopify US taxes setup, tax ID/registration status, shipping tax/override, accounting export responsible lead, last verification date, and freeze scope.
- Trigger
- Ads push budget into a new state and orders grow quickly, but tax responsibility, delivery promise, and dispute source are not reviewed together.
- First check
- Review that state by orders, tax state, fulfillment timing, dispute reasons, and support issues, not ROAS alone.
- Do not
- Do not keep scaling only because ad cost is low; a new state can add tax, fulfillment, and payment risk together.
- Minimum worksheet fields
- New-state orders and revenue; Tax liability signal; Delivery promise hit rate; Refund / dispute reason distribution
- Continue boundary
- Use small-traffic observation and weekly review; do not expand the same state before tax responsibility or dispute source is located.
- US Risk Evidence Sheet
- US Risk Evidence Sheet row: new state, orders/revenue, ad channel, tax-liability signal, fulfillment timing, refund/dispute reasons, weekly reviewer, and escalation record.
State nexus verification actions
- State facts: Write state, trailing sales or order count, ship-from location, and whether inventory or 3PL touches the state; do not hardcode permanent thresholds in the lesson.
- System signal: Record Shopify tax liability insights potential liability reason, potential liability date, registration state, and tax ID instead of treating the signal as a tax authority conclusion.
- Outside verification action: Turn state tax authority guidance, Streamlined Sales Tax remote-seller guidance, or tax-advisor review into an action and date; while unclear, only low-risk orders continue.
- Growth boundary: Review new-state budget, delivery promise, and dispute source together. Before the nexus check closes, strong ROAS is not enough reason to scale.
Order review actions
Before fulfillment, decide one of six moves: continue, pause, verify, cancel, refund, or refund to stop loss and accept the dispute.
This is the center of dispute governance. High-risk orders should not auto-fulfill; review actions must be visible to support, fulfillment, finance, and the people responsible for payments.
Choose a case: Continue
- When
- Low-risk order with aligned address, payment, inventory, and promise.
- Proof
- Order details, successful payment, fulfillable inventory, confirmation email.
- When
- Risk signals unexplained, or shipping/billing/IP conflict.
- Proof
- Fraud analysis, review note, customer contact record.
- When
- Order may be real but needs billing, address, phone, or purchase intent confirmation.
- Proof
- Customer reply, call/email log, updated order note.
- When
- Clustered risk signals, no customer response, repeated-card orders, or card testing.
- Proof
- Cancellation reason, refund or uncaptured record, inventory restock.
- When
- Product or promise cannot be fulfilled and shipping would increase dispute risk.
- Proof
- Refund receipt, customer notice, page or process fix record.
- When
- Evidence gaps cannot be fixed, the page promise really failed, or a promised refund lacked proof; fighting would waste fees, support time, and account risk.
- Proof
- Refund or accept-loss reason, ARN/refund record, customer notice, page/process fix, and next stop condition.
Where does a high-risk order stop before shipping, and when a chargeback arrives, do I submit evidence or stop the loss?
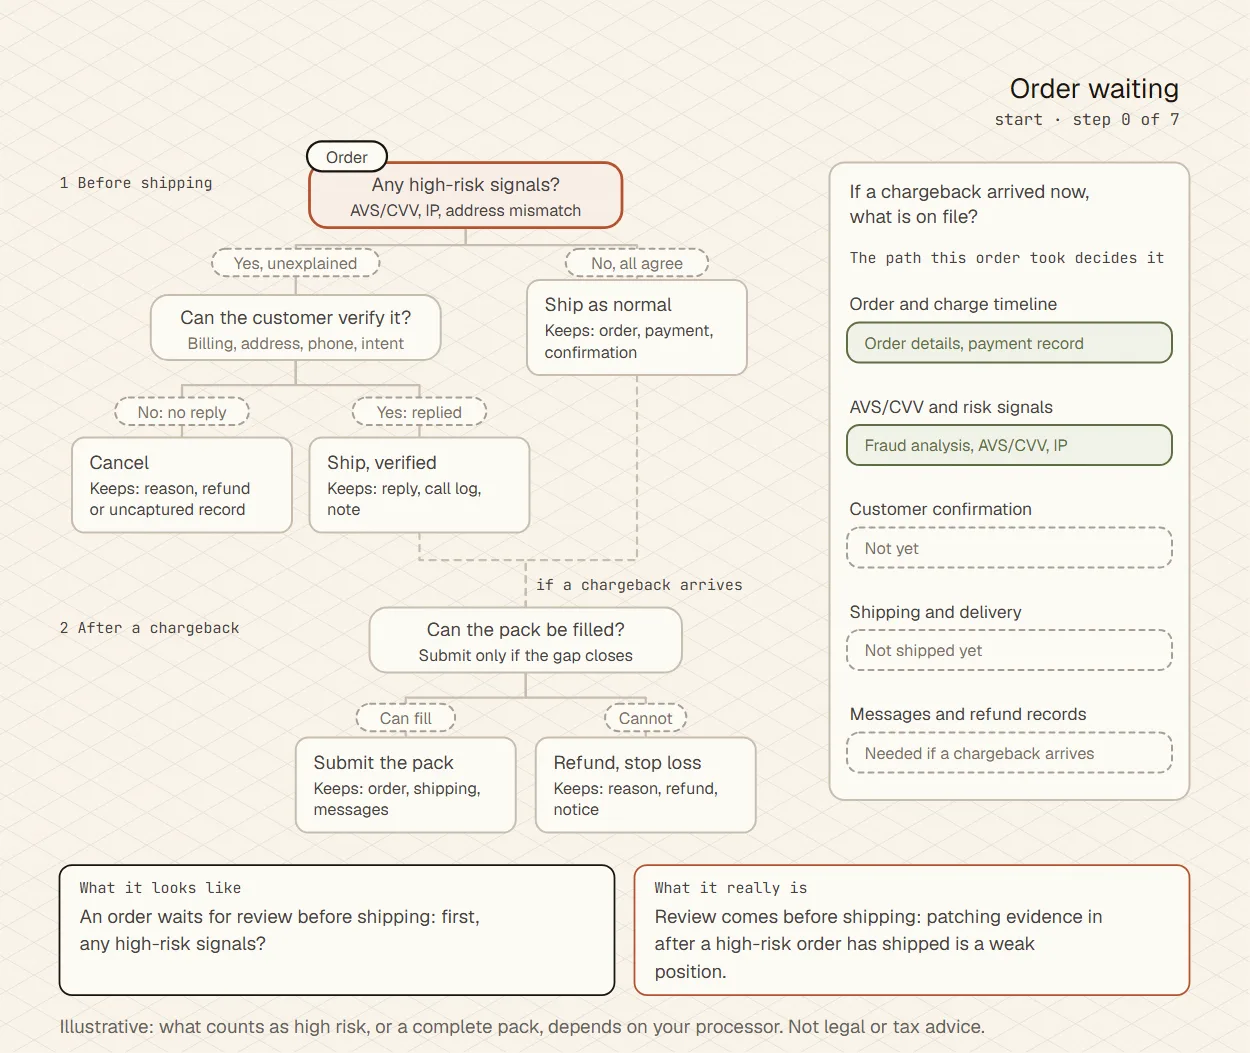
As text: the whole walk-through
- Held to verify The signals are unexplained: the order is held, not captured automatically and not shipped.
- Held to verify The warehouse has stock and wants to ship first: blocked, because with no verification there is no customer confirmation to submit if a chargeback arrives.
- High-risk order shipped The customer replies and confirms: the reply and the call or email record stay on the order, and only then does it ship.
- High-risk order shipped The parcel is signed for and it looks complete, but a signature shows delivery, not the cardholder’s authorisation.
- Chargeback in A chargeback arrives: check the evidence pack for what is missing and whether it can be filled.
- Chargeback in The messages and refund records are filled in: only a gap that can be closed is worth submitting.
- Pack submitted The pack goes in only once it is complete; the issuer usually decides, so a win is not guaranteed.
Illustrative: what counts as high risk, or a complete pack, depends on your processor. Not legal or tax advice.
Monthly pause/continue
Tax registration not read back
| Stop here | Go |
|---|---|
Do not scale into a state before registration, nexus, or rate is confirmed. | Confirm registration, applicable market, and rate source first. |
| Evidence Registration record, rate source, and review date. | |
Chargeback evidence incomplete
| Stop here | Go |
|---|---|
Do not submit the dispute while delivery, communication, or refund records are missing. | Complete order, tracking, communication, and refund evidence first. |
| Evidence Evidence pack and submission record. | |
Order risk not verified
| Stop here | Go |
|---|---|
Do not ship or keep charging before a high-risk order is verified. | Verify address, payment, and communication, then ship or cancel. |
| Evidence Verification record and support note. | |
Rising disputes must update order review and page promises.
US risk governance starts before a dispute. Review tax responsibility, dispute reason, SKU, channel, and support records each month.
- Tax liability unclear, but checkout already collects: Pause US scaling and document state liability, registration, exports, and professional confirmation.
- High-risk orders cluster by channel: Tighten order review for that channel; use manual capture or verify before fulfillment.
- Product not received rises for one SKU: Check carrier, delivery promise, tracking, and support messages; fix unstable page promises.
- Product unacceptable rises: Inspect product promise, specs, images, and fulfillment; pause ads and fix pages when needed.
- Monthly fraud/dispute ratio enters warning zone: Do not leave it in finance notes; update order review, support playbook, page promise, and channels.
Turn the risk table into the next action
Tax, orders, and monthly fraud/dispute rates each need their own conclusion.
Work through the items below to turn each tax trigger, evidence gap, or order-review result into a scoped action. Keep the selectors, tables, and evidence builder as they are, then write the decision back into your operating notes.
- Two lines, two conclusions: A tax signal is a review queue and a dispute signal is an order action; do not merge them into one green light. Shopify calculating or collecting tax does not mean the team has completed a state-responsibility decision; a delivery scan does not mean an order has enough dispute evidence. The state line needs the state, period facts, system signal, inventory or fulfillment connection, current registration status, and next reviewer. The order line needs the buyer timeline: page promise, checkout charge, order confirmation, capture, fulfillment scan, support explanation, and refund action. When a 20oz tumbler gets a tax-liability signal in one state, freeze scaling into that state instead of zeroing all US orders. If high-risk orders or delivery disputes also appear that week, order review may pause capture, verify, cancel, or refund; it does not replace the state review. Separate scopes keep one order from closing a whole market and keep a tax setting from automatically releasing the warehouse. Name whether the row is a state review, order risk, dispute evidence, or monthly-ratio issue instead of writing “US risk is normal.” Give the tax and order lines separate pause scopes, owners, and external-review or evidence deadlines. Write recovery conditions back into ads, checkout, order review, and the fulfillment queue, then name which action is actually restored.
- Treat a dispute as a case file: Each proof supports only its own part of the story; do not turn 20 orders into one score. For “item not received,” ask what delivery window the buyer saw, what later happened to the parcel, and when the team explained or repaired it. For an unrecognized transaction, ask what payment, address, customer confirmation, and order review preserved. A delivery scan supports a fulfillment trail but not automatically cardholder recognition; a support email shows communication but cannot erase the page promise at purchase. Put those proof limits in the case file so one screenshot does not become a generic response template. Do not give 20 orders one attractive score in monthly review. Separate normal delivery, address or risk-signal exceptions, delays, refunds, ad sources, and states; classify them as may continue, evidence needed, refund-to-stop-loss, page repair, or state review. The most common class becomes next week’s concrete change: rewrite delivery copy, add manual verification, narrow a source, or add a state record. Start with the reason-code question, then collect the order, page, payment, fulfillment, support, and refund timeline. For each proof, label what it supports, what it cannot support, and whether the case needs added evidence, refund-to-stop-loss, or escalation. Write next week’s action by order class rather than a total score, and narrow the relevant SKU, channel, carrier, or page promise when the same reason code repeats.
Quick Check
Shipping high-risk orders first is the expensive path.
Self-check: choose before reading feedback
Self-check not answered
What comes first for this order?
Note
Pick a move first
Verify before shipping
This move scales the risk
US Tax and Dispute pressure-check practice
When pressure rises, name the missing evidence before you release.
These four pressures are where US market work usually goes wrong. Click a pressure, then carry the first evidence, allowed move, and freeze rule into your own store review.
Choose a case: Tax collection is on
- Pressure
- Shopify has started collecting sales tax in some states, so the team assumes US tax is handled.
- Tempting wrong move
- Mistake calculation and collection for completed state liability, registration, filing, and remittance.
- Safer read
- A tax line is only a system action. Record state, reason, registration, accounting export, reviewer, and whether professional confirmation is needed.
- First evidence
- Shopify US taxes setup, tax liability insights, state notes, registration or tax ID, shipping tax or override, accounting export, and review date.
- Allowed move
- Continue low-risk orders, but pause US budget scaling until the state liability record is filled.
- Freeze rule
- When state, reason, and reviewer are unclear, tax collection is not permission to scale.
- Pressure
- A high-value high-risk order is waiting, and fulfillment wants to ship because tracking feels like enough evidence.
- Tempting wrong move
- Ship first and assemble dispute evidence after the bank notice arrives.
- Safer read
- Tracking is not universal evidence. Fraud or unrecognized disputes need AVS/CVV, IP, billing and shipping addresses, customer confirmation, and the order timeline.
- First evidence
- Fraud analysis, AVS/CVV, IP, billing and shipping, customer contact, review note, and captured or uncaptured status.
- Allowed move
- Pause and verify first. If the risk cannot be explained, cancel, refund, or leave payment uncaptured.
- Freeze rule
- When risk signals cluster and the customer does not respond, do not auto-capture or auto-fulfill.
- Pressure
- Product not received is rising for one SKU, and the team only wants to upload more tracking links.
- Tempting wrong move
- Treat every not-received case as a customer problem and only add a tracking number.
- Safer read
- When one SKU or channel concentrates the issue, inspect the delivery promise, carrier delays, proactive support, and ad promise.
- First evidence
- Tracking, delivery or scans, fulfillment time, shipping policy, order emails, support messages, and channel/SKU distribution.
- Allowed move
- Fix the promise first, pause scaling in the problem channel, and reship or refund when needed.
- Freeze rule
- When the page promise exceeds real fulfillment capacity, do not keep advertising the same promise.
- Pressure
- The monthly fraud and dispute ratio starts rising, but the team only notes it in finance reporting.
- Tempting wrong move
- Treat disputes as finance loss and avoid changing order review, pages, or acquisition.
- Safer read
- A rising ratio is a payment-account stability signal. Break it down by SKU, channel, region, and reason code, then update review rules and page promises.
- First evidence
- Payment dashboard, Shopify order export, chargeback reason codes, channel or ad source, SKU/region distribution, and support records.
- Allowed move
- Tighten review for high-risk channels, adjust page promises and support playbook, and pause the problem SKU or channel when needed.
- Freeze rule
- Before the concentrated source is identified, do not expand the same SKU or channel budget.
US tax and dispute risk: what to record
Turn US tax and dispute risk into a reusable record.
Before writing it down, check the point: this does not say US is open. It records which states need review, which orders need pause, which reason codes need evidence, and when monthly ratios trigger tightening.
US tax and dispute: points to record
- One-line decision: State whether this US risk is tax responsibility, order risk, dispute evidence, or monthly ratio warning, then name the current action.
- First evidence: Name the first missing item across state liability, Shopify setup, order risk signal, reason-code evidence, page/support promise, and monthly ratio.
- Allowed move: Choose one move: continue, pause/verify, cancel, refund, add state tax record, pause channel, or escalate confirmation.
- Evidence sheet row: Write state or order ID, reason code/tax trigger, first evidence, last verification date, responsible lead, escalation record, and freeze scope.
- Evidence Submission Pack: One-page order timeline, reason-code evidence map, screenshot labels, file names, submission deadline, evidence gap, and refund-to-stop-loss choice.
- Freeze rule: When tax responsibility is unclear, high-risk orders are unverified, evidence does not match reason code, or rising ratio is not located, budget and fulfillment do not move first.
Judgment: This is a classroom risk record in the current browser. Decision condition: Only take it to limited human review after the quick check is correct and every field is filled. Evidence: It records the current state trigger, reason-code case, order move, pressure selection, and worksheet fields. Scope: It does not connect to Shopify, payments, ads, orders, customers, or production data. Take away: The exported JSON is preparation for review only. Saved, restored, or exported does not mean a tax conclusion, dispute outcome, payment approval, or market release.
No checkpoint finished in this lesson yet. Start with “Go to the exercise”.
Self-check not answered
FAQ
- Why does this lesson start with one disputed order?
Because US risk is too easy to collapse into one label. One order separates sales tax, capture, shipping, refund promise, and chargeback evidence so tax, order review, support, fulfillment, and payment teams know which evidence they own.
- If Shopify already collects US sales tax at checkout, why am I not automatically compliant?
Tax calculation and collection do not prove registration, filing, remittance, state liability, or automated filing is complete. Check Shopify tax liability insights, registration state, filing responsibility, accounting export, and external tax confirmation before scaling.
- When tax liability insights flags a state, what should I do first?
Do not start by increasing ad budget. Export that state's orders, sales, tax setup, registration status, fulfillment history, trailing sales or order count, ship-from location, and whether inventory or 3PL touches the state into the US Risk Evidence Sheet. Tax liability insights is a verification entry point, not a tax authority conclusion. If the boundary is unclear, pause state scaling or escalate to external tax confirmation.
- When AVS/CVV, IP, or address signals mark an order high risk, should I capture and ship first?
Do not default to capture and ship. Review fraud analysis, AVS/CVV, IP, billing address, shipping address, email, and order history first. For high-risk orders, use manual capture, verification, cancellation, or refund before fulfillment.
- For Product not received or Fraudulent chargeback reason codes, what evidence should I prepare?
Match evidence to the reason code. Product not received needs tracking, delivery scan, ship date, supplier, carrier, promised SLA, delay communication, and page promise. Fraudulent needs AVS/CVV, IP, billing address, order confirmation email, statement descriptor, and manual review notes. The final Evidence Submission Pack should include a one-page order timeline, reason-code evidence map, page and policy snapshots, support communication, screenshot labels, file names, submission deadline, and evidence gap.
- If a refund was processed, why can Credit not processed still become a dispute?
A buyer may still dispute when the refund path is not visible. Record refund time, amount, payment gateway record, ARN, support confirmation, email notice, and expected arrival window; do not rely on a support note saying it was refunded. If the page promise or refund process really failed, send proof, notify the buyer, and refund to stop loss or accept the dispute instead of fighting mechanically.
- Why do Visa VAMP or monthly dispute ratios affect daily order review?
Monthly ratios should not wait until month end. This boundary was checked as of 2026-10-03; re-check when Visa monitoring, payment-provider rules, Shopify chargeback guidance, or state sales-tax guidance changes. Ratios decide whether high-risk orders need manual capture, which SKUs or channels tighten, which page promises change, and which support scripts explain earlier.
- What should the US tax and dispute record include?
Write order ID, transaction ID, state, tax state, risk signals, reason code, payment record, support ticket, fulfillment record, page and policy snapshots, refund or ARN, current move, responsible lead, last verification date, and next review moment. Do not only write “US is open.”
Compliance paths after tax and dispute review
After tax and dispute review, route remaining EU and page-promise questions to the matching path.
These links only help continue evidence-boundary checks. They do not settle tax responsibility, dispute outcomes, or product claims; review each item against the target market and current system.
Return to the Compliance Risk Hub
- EU GPSR, VAT, and IOSS: check operating responsibilities separately: Read product-safety ownership, tax display, and low-value parcel declarations separately; do not treat one payment or dispute record as an EU go-live basis.
Sources
Public copy cites official checking paths.
This material does not make tax conclusions or guarantee dispute outcomes. Official sources anchor Shopify tax setup, liability insights, chargebacks, reason-code evidence, fraud analysis, manual capture / Flow, and Visa VAMP monitoring context.